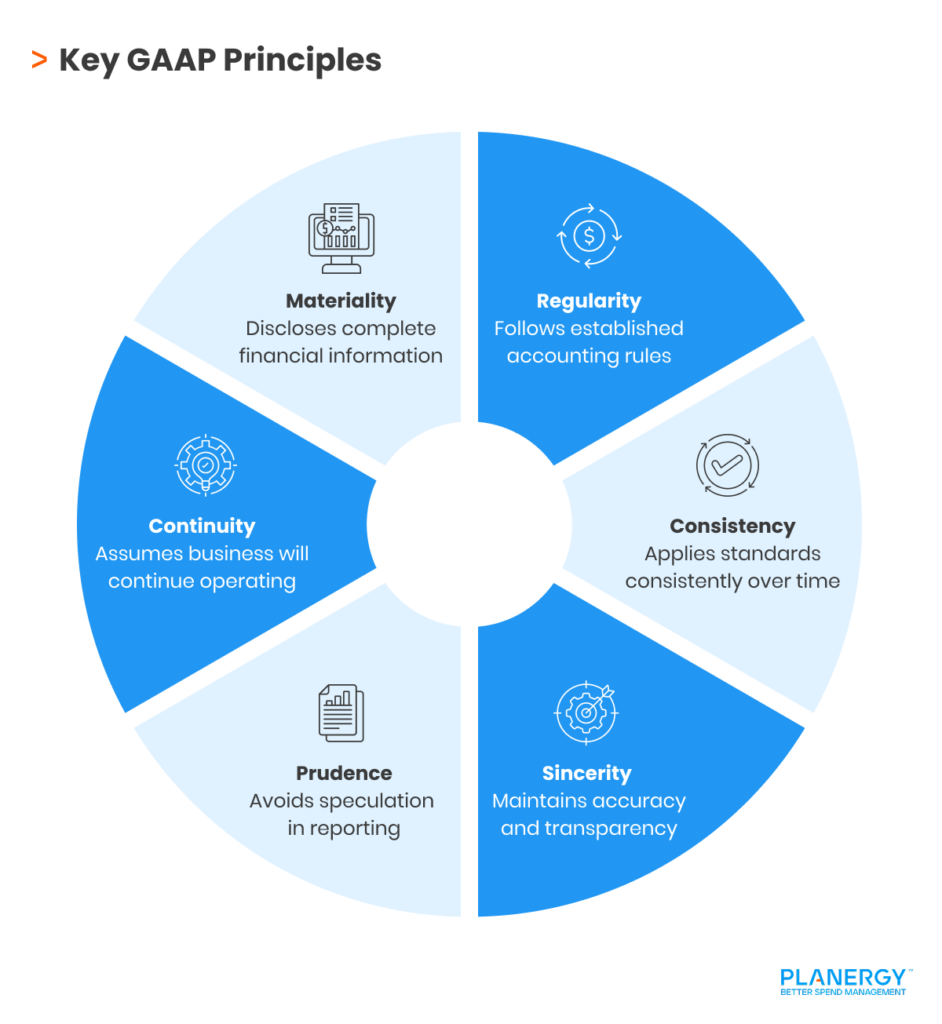
Whether you’re a small, local business or a national corporation, adhering to Generally Accepted Accounting Principles (GAAP) is essential.
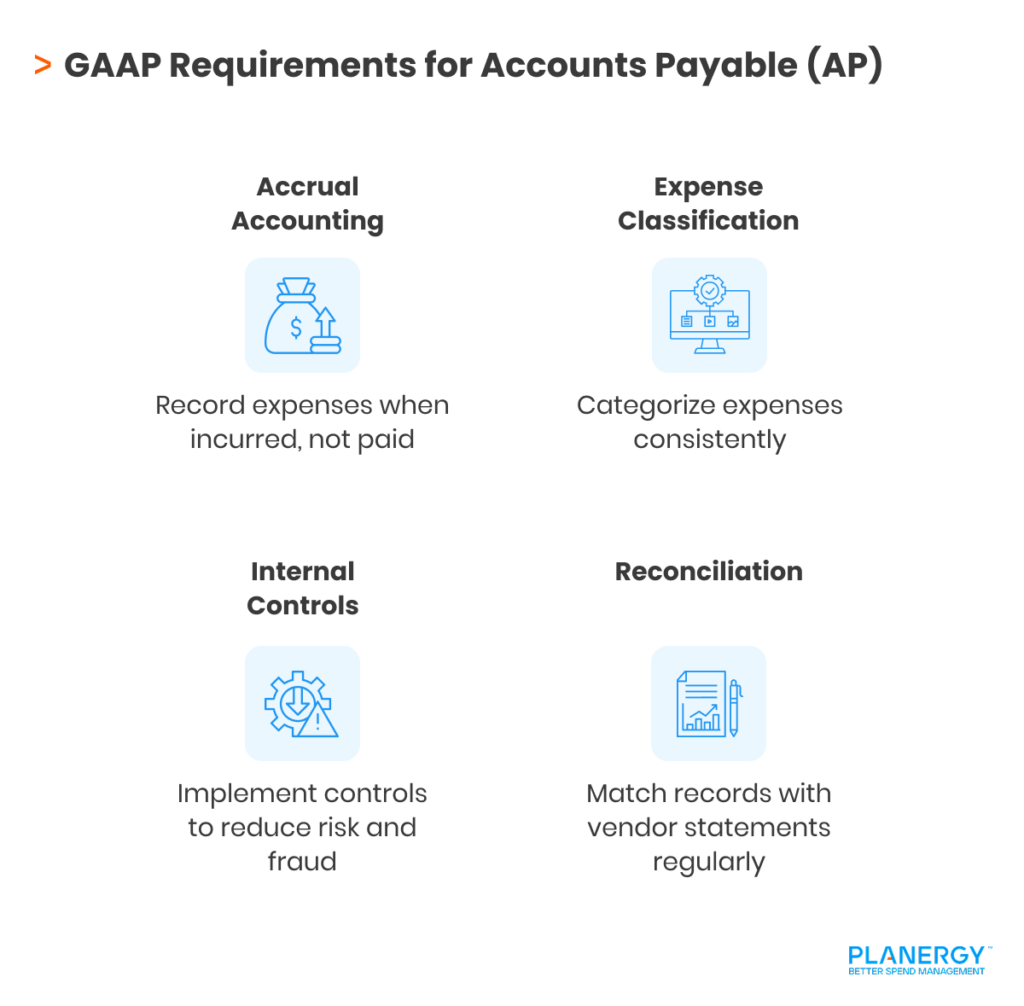
Adhering to GAAP and other accounting rules like the International Financial Reporting Standards (IFRS), helps a business structure its accounts payable process to be in compliance with rules and regulations while ensuring financial statement accuracy.
What is Accounts Payable?
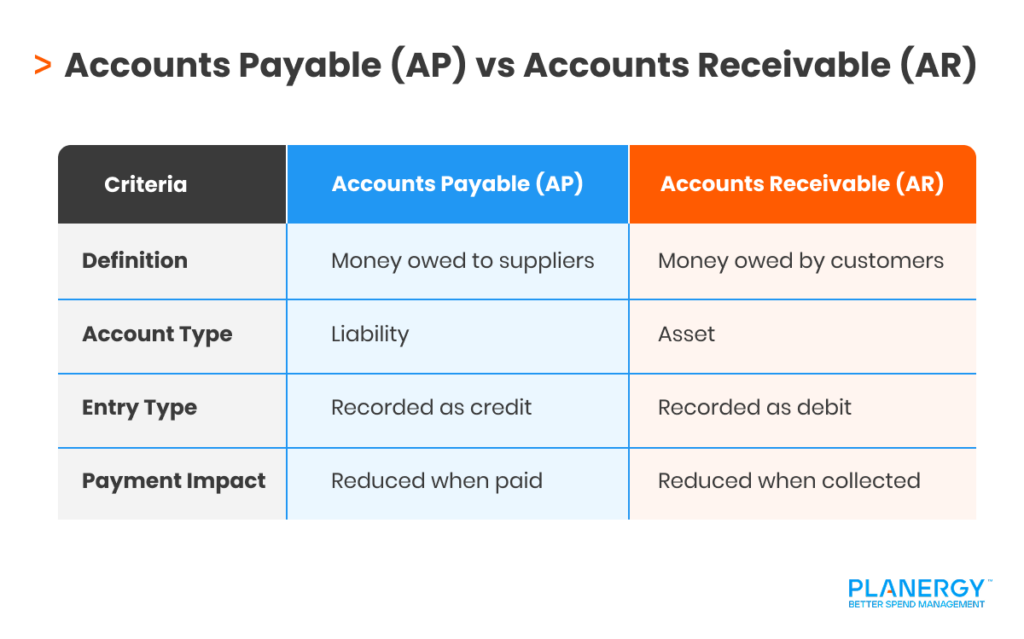
Accounts Payable is debt representing money owed to vendors and suppliers for materials or services purchased on credit.
The Accounts Payable balance recorded on a company’s balance sheet is considered a current liability because it is considered a short-term debt that will need to be paid by a certain date, which varies based on the credit terms provided by the vendor or supplier.
Is Accounts Payable a Debit or a Credit?
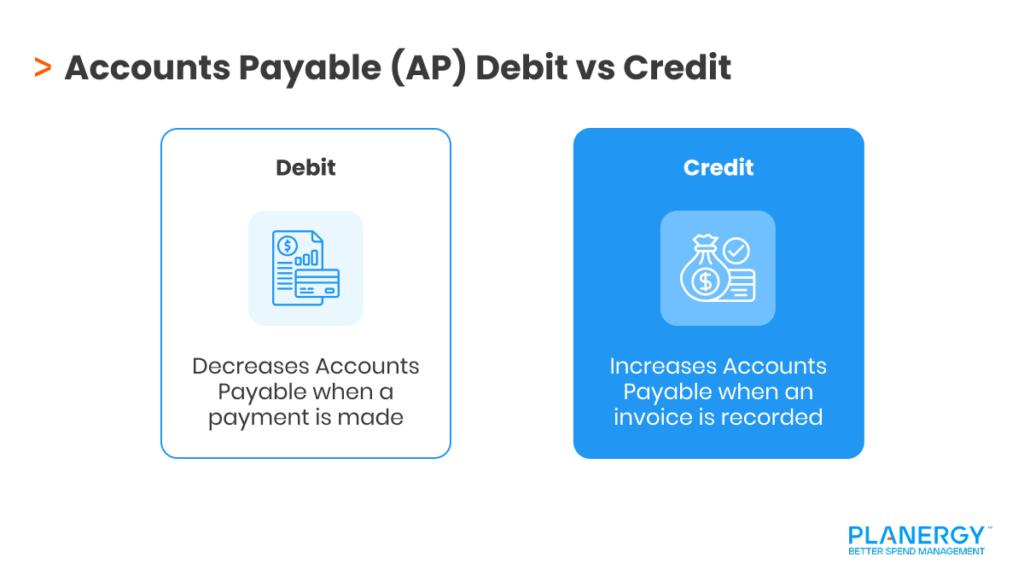
Accounts Payable is a liability account, so any new accounts payable invoice is recorded as a credit, which increases the accounts payable balance. When the invoice is paid, the Accounts Payable account is debited, decreasing the balance of the account since the invoice is no longer due and payable.